
When a loan slips, the calls start — and almost nobody being called knows that the caller is working inside a written rulebook. The Reserve Bank issued it as a circular to the lenders themselves, so it is the lender who is answerable when an agent crosses it, not some agency you have never heard of.
The circular is RBI/2022-23/108, dated 12 August 2022, on the responsibilities of regulated entities employing recovery agents. Being overdue does not suspend any of it. A genuine default gives a lender the right to recover; it does not give anyone the right to frighten you.
The hours, which is the part most often broken
The circular bars regulated entities and their agents from persistently calling a borrower, and from calling before 8:00 a.m. or after 7:00 p.m., for recovery of overdue loans. A call at 9 p.m., or the tenth call of one day, is outside the rule regardless of how far behind the account is.
What an agent may never do
On harassment the wording is deliberately broad. The circular says regulated entities shall strictly ensure that they or their agents do not resort to intimidation or harassment of any kind, either verbal or physical, against any person in their debt collection efforts.
- Publicly humiliating you — including telling neighbours, relatives or your employer about the debt.
- Intruding on your privacy, or on the privacy of your family.
- Sending inappropriate messages by phone or social media.
- Making threatening or anonymous calls.
- Making false or misleading representations about what will happen if you do not pay.
Note the phrase "any person". It covers your family and your references too, not only the borrower — which is why calling a relative to apply pressure is not a grey area.
Which lenders this binds
Commercial banks including small finance banks and regional rural banks, all-India financial institutions, every NBFC including housing finance companies, urban and state and district central co-operative banks, and asset reconstruction companies. Payments banks are outside it, and microfinance loans are governed by their own 2022 master direction instead.
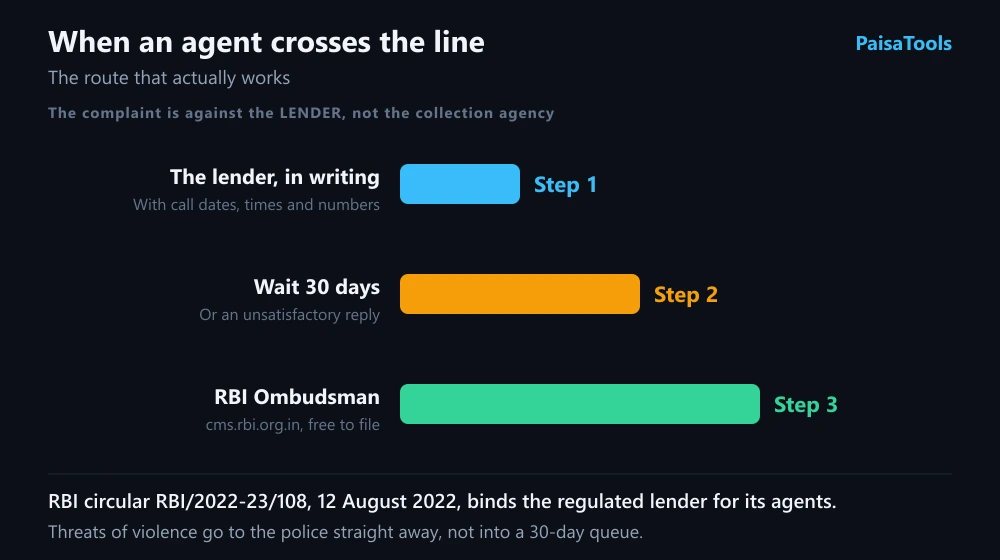
That list matters when you complain, because it decides who the complaint is actually against — the regulated lender, not the collection agency.
The escalation that has teeth
Complain to the lender first, in writing, with dates and times of the calls and the number they came from. A call log screenshot is the evidence that does the work here. If the lender does not resolve it within 30 days, or replies unsatisfactorily, the complaint goes to the RBI Ombudsman through the complaint management system at cms.rbi.org.in — the same route as any other banking grievance, and it costs nothing to file.
Threats of violence are a separate matter and belong with the police immediately, not in a 30-day queue.
See what your loan actually costs each monthFrequently asked questions
- Can a recovery agent visit my home?
- A visit is not banned outright, but everything in the harassment clause still applies to it — no intimidation, no public humiliation, and no intrusion on your family's privacy.
- Can they call my family or my employer?
- The harassment clause is written as protecting "any person", not only the borrower, and publicly disclosing the debt to people around you is listed among the prohibited acts.
- Does being genuinely in default remove these protections?
- No. The circular draws no distinction based on how overdue the account is. Recovery remains the lender's right; the conduct rules apply throughout.
- Where does a complaint go if the lender ignores it?
- To the RBI Ombudsman via cms.rbi.org.in, after giving the lender 30 days to resolve it or receiving an unsatisfactory reply.